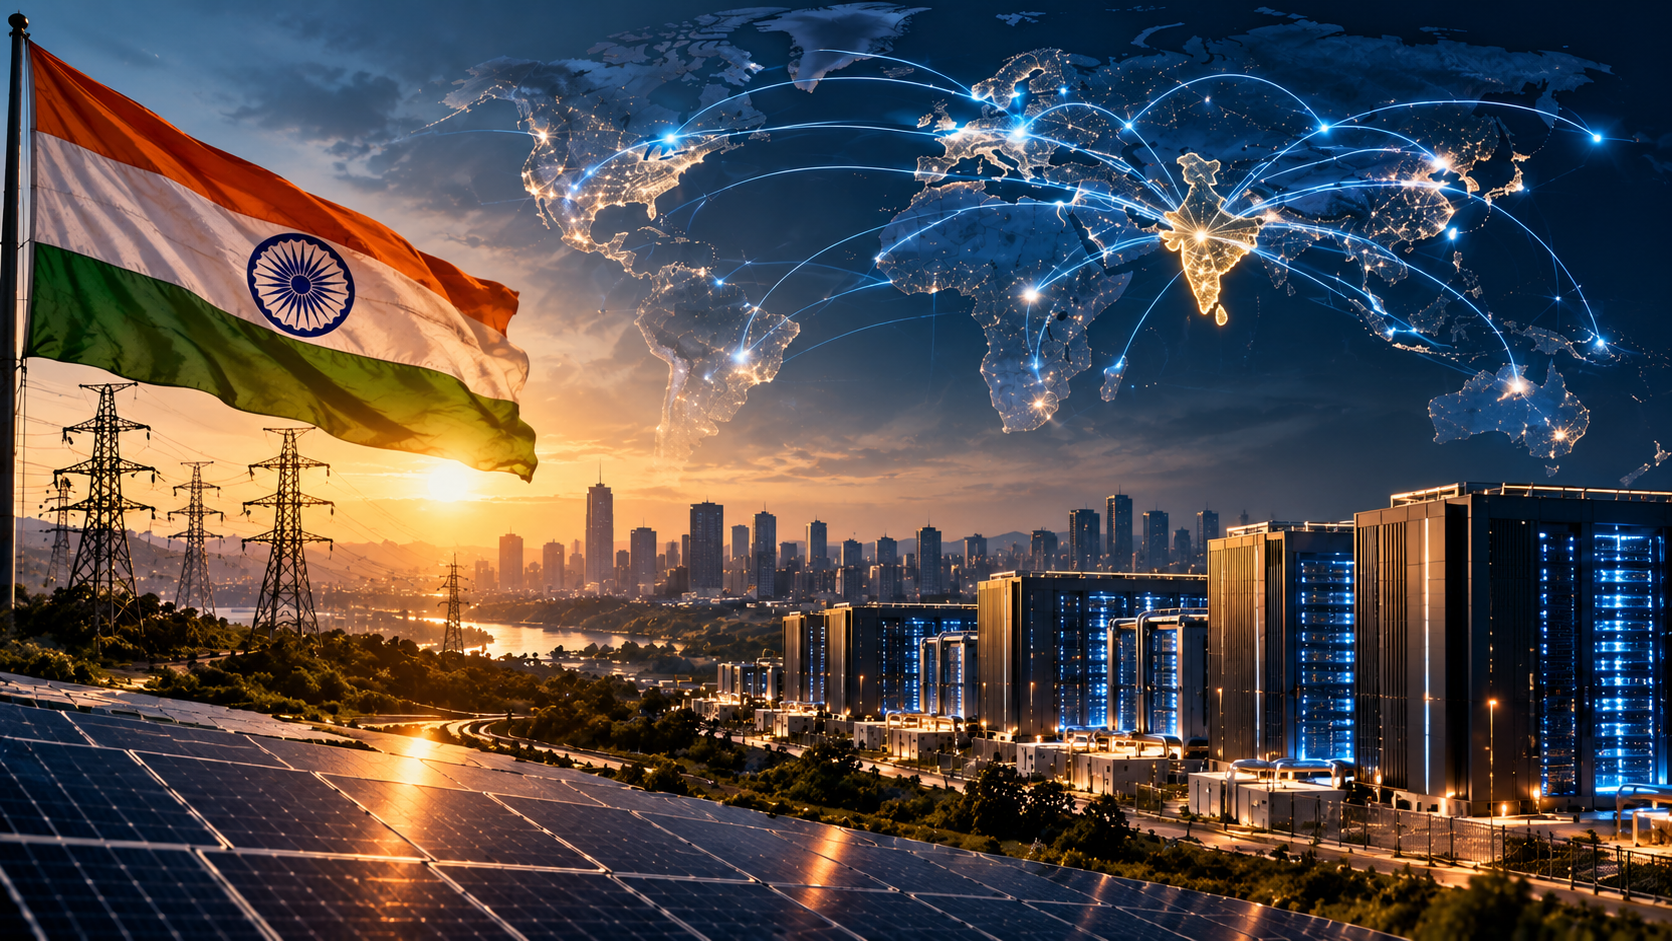
- A country’s ability to attract technology investment may no longer depend solely on its talent pool, internet penetration or regulatory environment.
- The next generation of digital infrastructure may be constrained less by how much data the world can produce than by how much electricity it can reliably devote to processing that data.
- The nations best positioned for the next stage of the digital economy may not necessarily be those with the largest technology sectors today, but rather those capable of providing the energy and infrastructure that the technologies of the future will require.
For much of the digital age, the location of data seemed almost irrelevant. Data could move across borders in milliseconds, and the internet gave the sense that economic activity was increasingly able to break free from the constraints of geography. That premise is becoming harder to maintain.
The growth of AI, cloud computing and digital services is creating new physical demands for the digital economy. Data centres consume huge amounts of power and require stable grids, cooling systems, land, and increasingly secure access to infrastructure. As nations vie to attract the next generation of digital investment, access to such resources may become as critical as access to capital or technology.
This poses an emerging geopolitical question: where can the world afford to put its computing power? The answer will be determined not only by technological capacity, but also by energy supply, infrastructure, regulation and the extent to which states can provide dependable digital ecosystems.
The geography of data, then, may increasingly become a geography of economic power. Countries that can combine plentiful and reliable energy with connectivity, infrastructure and a business environment capable of supporting large-scale computing could gain an advantage in the next phase of the digital economy.
The Digital Economy Has a Physical Footprint
The digital economy may seem weightless, but the infrastructure that underpins it is anything but. Every search, video stream, cloud application and AI query relies on physical systems that use electricity, occupy space and require cooling. Data centres are at the heart of this infrastructure, evolving from relatively niche facilities into key components of modern economic activity.
The growing adoption of cloud computing and AI is transforming the scale of this demand. The training and operation of increasingly complex AI models require significant computing power, while the broader shift towards cloud-based services is driving greater demand for data storage and processing. As a result, countries looking to attract digital investment will increasingly need to consider a question that was once thought to be at the periphery of technology policy: Do they have the power and infrastructure to support it?
Electricity is especially critical, as data centres are not only large consumers of power but also require a dependable supply. Interruptions can disrupt services and impose significant costs on operators. Cooling adds another layer of resource demand, particularly in areas where temperatures are high or water is limited. As a result, connectivity, grid capacity and land are becoming part of the infrastructure needed to host the digital economy.
This changes the traditional definition of digital competitiveness. A country’s ability to attract technology investment may no longer depend solely on its talent pool, internet penetration or regulatory environment. Energy availability, infrastructure capacity and the reliability of basic utilities are playing an increasingly important role in the technology equation.
AI Is Changing the Economics of Data Centres
Artificial intelligence is not simply increasing demand for data centres; it is changing the type and scale of infrastructure they require. Traditional cloud services rely heavily on predictable patterns of storage and computing, whereas AI workloads can require large concentrations of high-performance computing capacity. Training advanced models and serving them to millions of users can therefore place substantial demands on power, cooling and network infrastructure.
This is already influencing where technology companies and data-centre operators choose to invest. Locations are increasingly assessed not only for their proximity to users or availability of fibre connectivity, but also for their access to electricity and the ability of local grids to accommodate large new loads. In some markets, the availability of power has become a constraint on how quickly new data-centre capacity can be brought online.
The economics of AI therefore extend beyond the cost of chips and computing equipment. The availability and price of electricity can increasingly shape the cost of intelligence itself. A country with abundant and reliable power may be able to attract data-centre investment more easily than one with advanced digital capabilities but constrained energy infrastructure.
This could create a new form of competition for digital investment. Countries are already seeking to position themselves as attractive locations for data centres by expanding power generation, strengthening grids, developing digital infrastructure and offering investment incentives. As AI adoption accelerates, the ability to provide the physical foundations for computing could become an increasingly important component of technological competitiveness.
The implication is significant: the next generation of digital infrastructure may be constrained less by how much data the world can produce than by how much electricity it can reliably devote to processing that data.
Energy Is Becoming a Technology Constraint
For many years, technology policy and energy policy were treated as two separate policy areas. That distinction is now becoming harder to maintain. As demand for computing power grows, access to affordable and reliable electricity is becoming a constraint on the development of the digital economy. As a result, competition for technology investment may become increasingly intertwined with the race for energy.
This is especially important because electricity cannot be transported across borders as easily as capital, software or data. It is relatively easy for a firm to set up a software team in a new market, but it takes years to build the generation capacity, transmission networks and data-centre infrastructure needed to support computing at scale. This could give countries with reliable and abundant energy an advantage in attracting energy-intensive digital industries.
It is not just about the amount of electricity available. Reliability is just as important as supply. Data centres operate around the clock, making them particularly vulnerable to grid instability and power outages. At the same time, the drive to decarbonise electricity systems is adding another layer to the technology policy equation for companies and governments, especially as companies come under increasing pressure to reduce the emissions associated with their digital infrastructure.
This creates a new policy dilemma. Countries are keen to attract data centres because they can bring investment, technology and economic activity. However, these facilities can also place significant pressure on electricity grids and other resources. Governments therefore need to weigh the economic benefits of digital investment against the infrastructure required to support it.
This is creating a new dimension to the geography of technological competition. The nations best positioned for the next stage of the digital economy may not necessarily be those with the largest technology sectors today, but rather those capable of providing the energy and infrastructure that the technologies of the future will require.
Conclusion
The digital economy was once associated with the idea that geography was becoming less important. Data could move instantly, businesses could operate across borders, and digital services appeared increasingly detached from physical location. The rise of AI is challenging that assumption.
As computing requirements grow, the foundations of digital activity are becoming increasingly physical: electricity, grids, land, cooling systems, connectivity and reliable infrastructure. This means that technological competitiveness may increasingly depend not only on who develops the next breakthrough technology, but also on who can provide the resources required to operate it at scale.
This does not mean that energy-rich countries will automatically become technology leaders. Talent, capital, innovation, regulation and digital infrastructure will remain critical. But the growing physical demands of computing are adding another dimension to the competition for technological investment.
The next phase of the digital economy may therefore be shaped by an unexpected constraint. In a world where data can travel almost instantly, the infrastructure required to process it cannot. The geography of computing is becoming a factor in the geography of economic power.
Archita Gaur is a postgraduate student at the School of International Studies, JNU. She specialises in the World Economy and has a strong interest in public policy, economic research, and governance. The views expressed are the author’s own.
 Anjali Singh
 Dr Mohmmad Rizwan